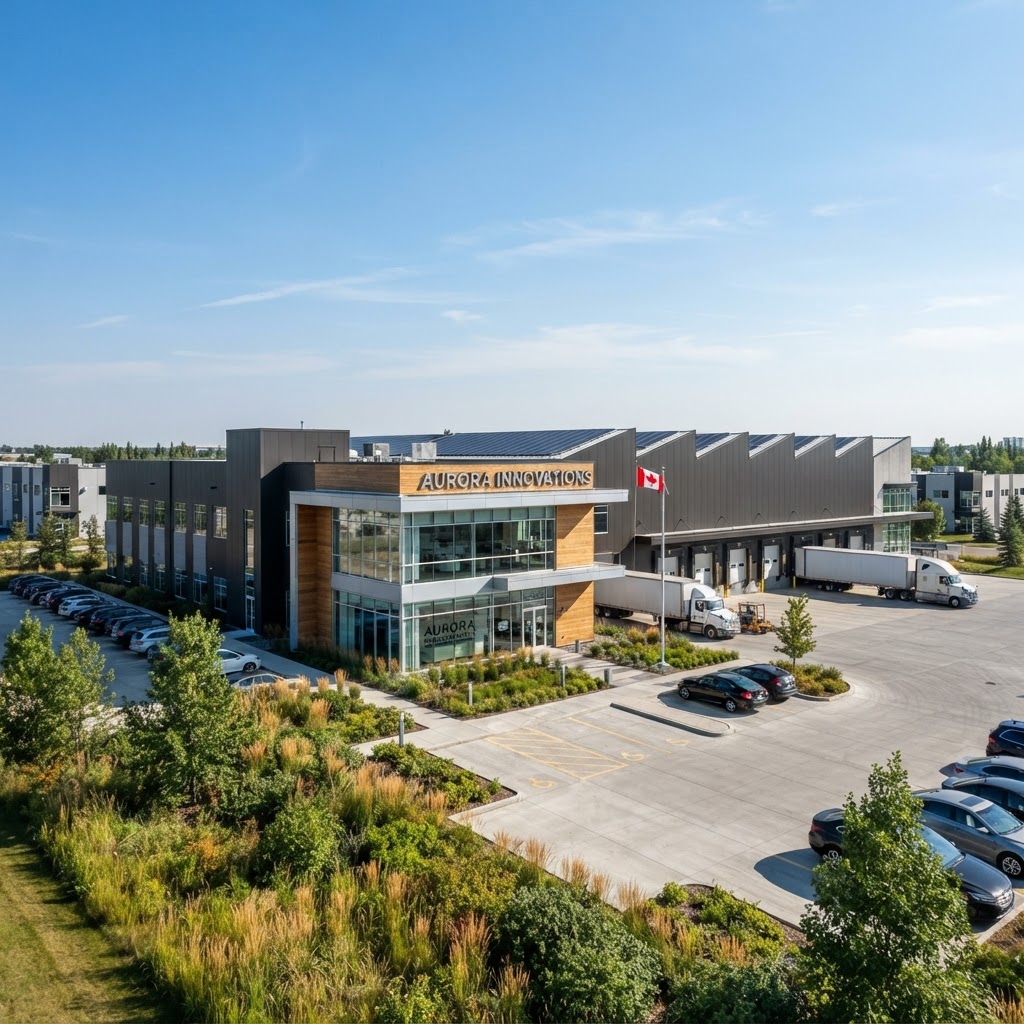
Buying Commercial Real Estate in Canada: A Guide for Businesses
A comprehensive guide for Canadian entrepreneurs looking to transition from leasing to owning commercial property. Learn about financing, zoning, and provincial legal differences to make an informed investment for your business.
The Strategic Shift: Why Canadian Businesses are Buying
For many Canadian entrepreneurs, the decision to move from a commercial lease to property ownership is a defining moment in their business lifecycle. Owning your own space offers stability against rising rents, provides a tangible asset for the balance sheet, and allows for complete control over the physical environment. However, the Canadian commercial real estate (CRE) market is significantly more complex than the residential sector. From the civil law nuances in Quebec to the land title systems in Alberta and British Columbia, understanding the landscape is vital. Before diving in, it is helpful to consult our AI Advisor to align your property search with your long-term business goals.
The Buy vs. Lease Analysis
The first step is a rigorous financial comparison. While leasing offers flexibility and lower upfront capital requirements, buying builds equity. In Canada, commercial mortgage rates and terms differ from residential ones, often requiring higher down payments (typically 25% to 35%). Business owners should use our Calculators to model the Total Cost of Occupancy (TCO).
Pros of Buying
- Equity Growth: Your monthly payments contribute to ownership rather than a landlord's profit.
- Tax Deductions: You can often deduct mortgage interest, property taxes, and capital cost allowance (depreciation).
- Control: You can renovate or expand the space to suit your specific operational needs without landlord approval.
Cons of Buying
- Capital Lock-up: A significant amount of cash is tied up in the down payment and closing costs.
- Maintenance Responsibility: You are responsible for the roof, HVAC, and all structural repairs.
- Reduced Agility: It is much harder to move if your business outgrows the space or needs to downsize.
Understanding Commercial Asset Classes
Not all commercial properties are created equal. The Canadian market generally categorizes business real estate into four main types:
- Industrial: Warehouses, manufacturing plants, and distribution centers. This sector has seen massive growth in hubs like the Greater Toronto Area (GTA) and Metro Vancouver due to the rise of e-commerce.
- Retail: Strip malls, shopping centers, and standalone storefronts. Zoning is particularly strict here regarding the type of business permitted.
- Office: From downtown high-rises to suburban professional buildings. The post-pandemic shift has changed the valuation of these assets significantly.
- Multi-Family: While residential in nature, buildings with five or more units are treated as commercial investments in Canada and require commercial financing.
Building Your Acquisition Team
You cannot navigate a commercial deal alone. A standard Canadian CRE team includes:
- Commercial Realtor: Unlike residential agents, they specialize in cap rates, net operating income (NOI), and industrial zoning.
- Commercial Mortgage Broker: To navigate Tier 1 banks, credit unions, and specialized lenders like the Business Development Bank of Canada (BDC).
- Real Estate Lawyer: Essential for reviewing the Agreement of Purchase and Sale and conducting title searches.
- Environmental Consultant: To perform Phase I and Phase II Environmental Site Assessments (ESA), which are almost always required by Canadian lenders to ensure the land is not contaminated.
The Canadian Financing Landscape
Financing a business property is based more on the property's income-generating potential and the business's financial health than the owner's personal credit score.
- Loan-to-Value (LTV): Expect LTVs between 60% and 75%. You will need to provide the remaining 25-40% as a down payment.
- Debt Service Coverage Ratio (DSCR): Lenders want to see that your business income can comfortably cover the mortgage payments, usually requiring a ratio of 1.25x or higher.
- Amortization: Typically shorter than residential, often 15 to 25 years, with terms (interest rate resets) every 1 to 5 years.
Provincial Legal and Regulatory Variations
Canada’s legal system for real estate is split, and understanding where you are buying is critical:
- Common Law Provinces: Most of Canada follows English Common Law. In provinces like British Columbia, Alberta, and Saskatchewan, the "Land Titles" system (Torrens system) is used, where the government effectively guarantees the title.
- Quebec: Real estate is governed by the Civil Code of Quebec. The terminology and process (using Notaries instead of just lawyers) are distinct. For example, an "Offer to Lease" or "Offer to Purchase" has different binding implications than in Ontario.
- Ontario and Atlantic Canada: These regions are often in transition from older "Registry" systems to modern "Land Titles" systems. In Ontario, you may encounter "Land Titles Absolute" or "Qualified" parcels, which affect how title insurance is handled.
For a deeper dive into these regional specifics, browse our Resource Library.
Due Diligence: The Critical Phase
Once an offer is accepted, the due diligence period (often 30-60 days) begins. This is where you perform a Health Check on the investment.
- Zoning Verification: Ensure your specific business activity is permitted. Municipalities like Calgary or Ottawa have specific bylaws regarding parking requirements, signage, and noise levels.
- Building Inspection: Assessing the HVAC, roof, and structural integrity. Commercial inspections are more technical and expensive than residential ones.
- Environmental Audit: Crucial for industrial sites to ensure no soil contamination exists from previous tenants, which could leave you liable for millions in cleanup costs.
- Financial Audit: If the property has other tenants, you must review their leases and payment history.
Taxation and Closing Costs
Budgeting for the purchase price is not enough. In Canada, you must account for:
- Land Transfer Tax (LTT): Varies by province. For example, a buyer in Toronto pays both provincial and municipal LTT, which can add tens of thousands to the cost.
- GST/HST: Commercial sales are generally subject to GST/HST. However, if the buyer is a GST/HST registrant, they can often claim an Input Tax Credit (ITC) or use a specific tax election to offset the tax at closing so they don't have to pay it upfront.
- Appraisal Fees: Commercial appraisals are significantly more expensive than residential ones, often costing $2,000 to $5,000+ depending on the complexity of the building.
Practical Tips for Business Owners
- Think About Future Growth: Buy a building that can accommodate a 20% increase in staff or inventory. It is cheaper to have extra space now than to move again in three years.
- Check the Estoppel Certificates: If the building has existing tenants, these documents confirm the terms of their leases and ensure there are no undisclosed disputes.
- Review the Property Tax Assessment: Commercial property taxes can be a massive annual expense; ensure the current assessment is accurate and not based on an outdated valuation.
- Consult the Community: Use our Q&A Community to ask other owners about their experiences with specific municipal planning departments or local commercial lenders.
Conclusion
Buying a business property in Canada is a marathon, not a sprint. By understanding the provincial nuances and building a robust team of experts, you can turn a real estate liability into a powerful business asset. For more detailed walkthroughs on the transition from tenant to owner, explore our Buying Guides to ensure you are fully prepared for your next move.
Related Articles
Related Questions
Should I lease or buy commercial space for my small business?
The lease vs. buy decision for your business depends on several key factors: When leasing makes sense: - Your business ...
00What are the best cities in Canada for real estate investment in 2024?
Top Canadian Cities for Real Estate Investment 1. Calgary, Alberta - Strong population growth - Relatively affordable...
521203Can I legally rent my basement apartment in Ontario?
Short Answer Yes, but only if it meets specific legal requirements. Requirements To legally rent a basement apartmen...
47892Is this condo reserve fund healthy? How do I evaluate?
How to Evaluate a Condo Reserve Fund Step 1: Review the Reserve Fund Study Every condo corporation in Ontario must ha...
41578